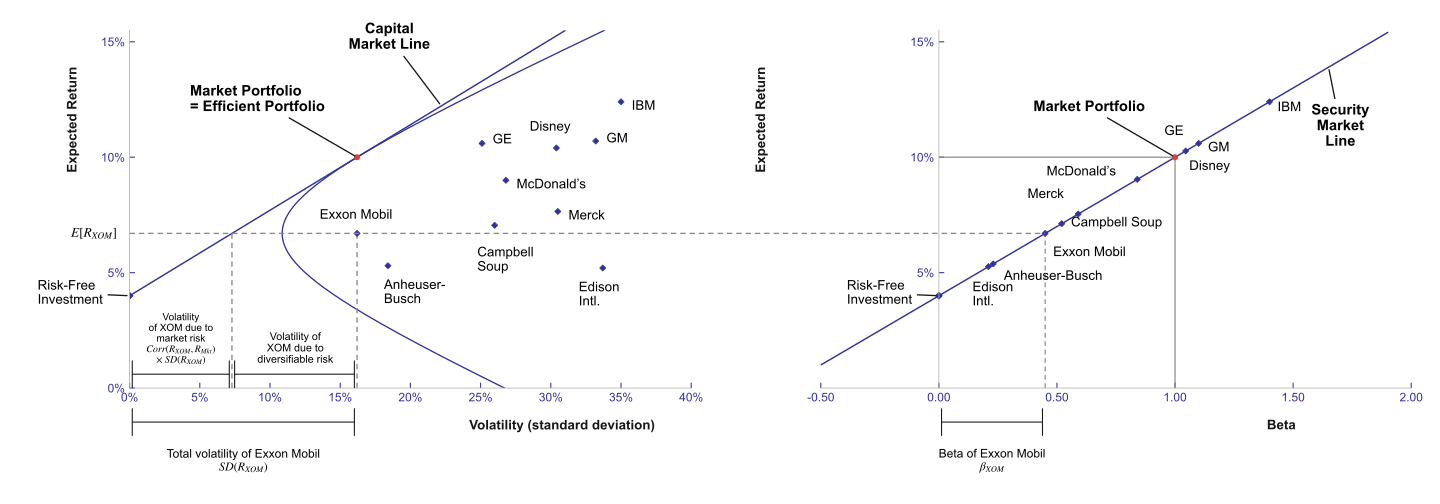
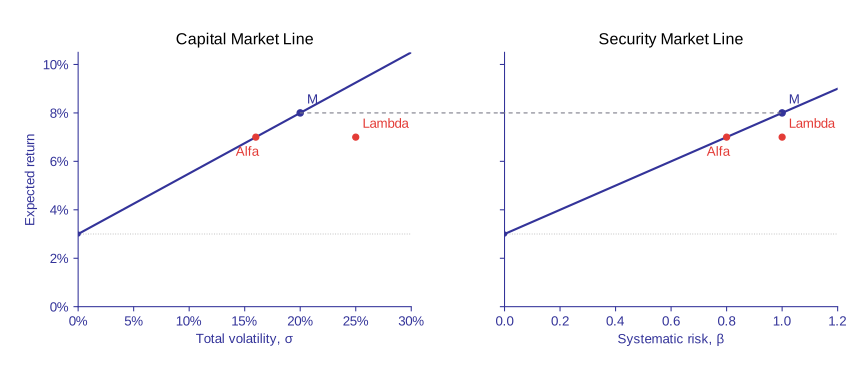
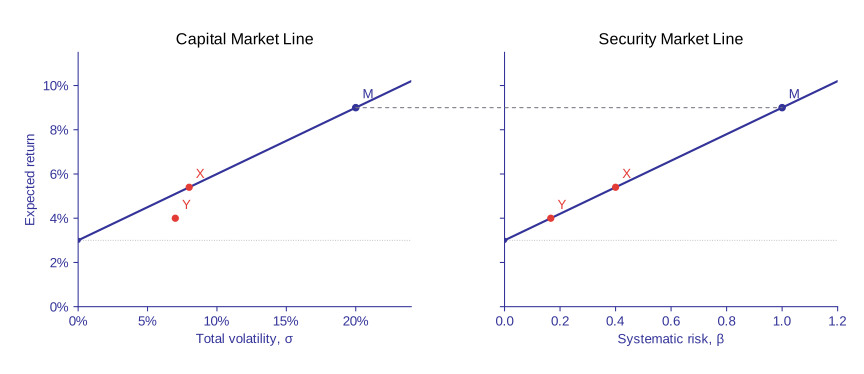
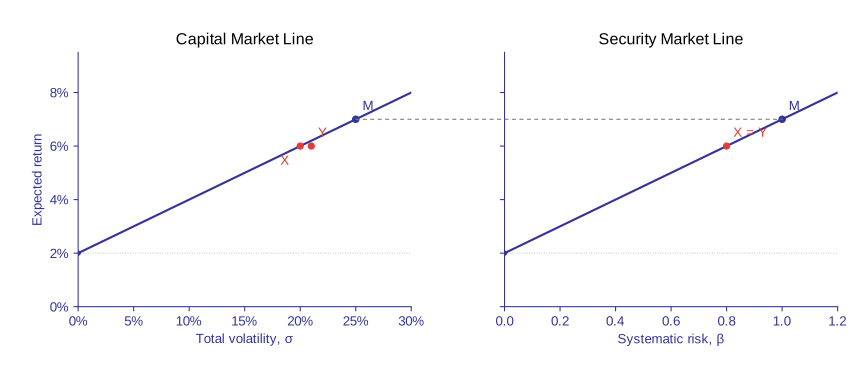
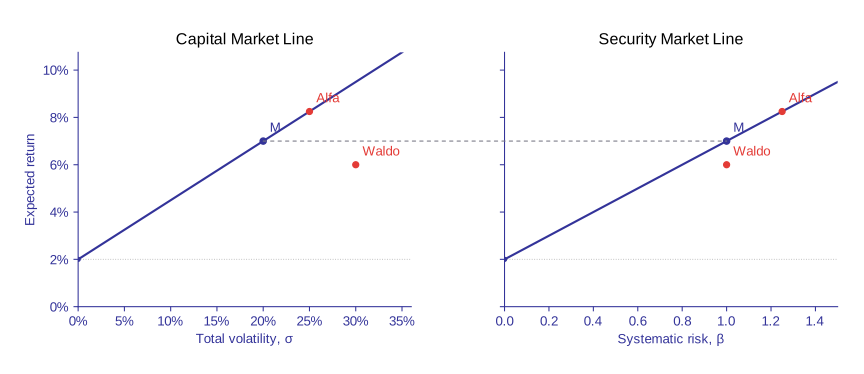
Draw both relationships, identify their axes and explain their scope.
- A.What do the CML and SML describe?
- B.Why does the tangency portfolio coincide with the market in CAPM equilibrium?
- C.What is the risk–return trade-off and an efficient portfolio?
- D.Can two portfolios with the same return, but 20% and 14% volatility, both be efficient?
- E.Does adding a risk-free asset improve the opportunity set?